MBA / PGDM

Understanding Inflation and Interest Rates: Forces Shaping the Economy
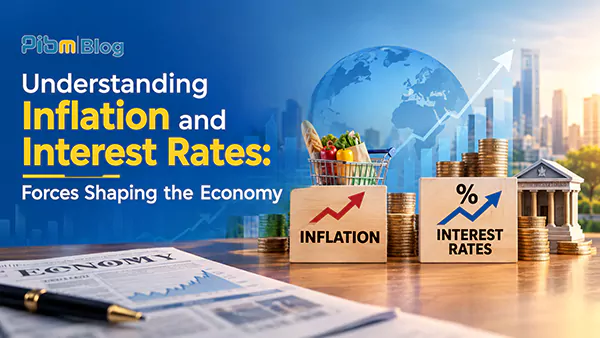
Table of Contents
- How Inflation and Interest Rates Are Correlated
- Understanding Inflation
- Types of Inflation
- What Are Interest Rates?
- Why Does the RBI Change Interest Rates?
- The Relationship Between Inflation and Interest Rates
- Impact on Consumers
- Impact on Investors and Financial Markets
- India's Experience with Inflation and Interest Rates
- Global Perspective
- Conclusion
How Inflation and Interest Rates Are Correlated
In finance, business, and capital markets, few words carry as much fundamental importance as inflation and interest rates. In everyday life, we are constantly affected by these two critical economic forces. Although we hear these terms regularly, understanding how deep their roots run through the economy is essential. Conceptual clarity on these concepts is a must, as they directly dictate our daily living costs, investment yields, household expenditure, business financing decisions, and overall national economic growth.
A packet of chips that used to cost ₹10 now costs ₹20 for the same quantity—if not less. That is a tangible example of inflation. Similarly, if banks increase the interest rate on home loans from 8% to 9%, buying a house becomes substantially more expensive because borrowers have to pay higher equated monthly installments (EMIs). These changes are closely connected, forming one of the most important relationships in macroeconomics.
Inflation and interest rates are linked so tightly that they constantly influence each other. When inflation rises, the Reserve Bank of India (RBI) often increases interest rates. Central banks do this to make borrowing more expensive for individuals and businesses; higher borrowing costs encourage people to save rather than spend, which eventually reduces aggregate demand and stabilizes prices. Conversely, when inflation is low and economic growth slows, the RBI may reduce interest rates to encourage borrowing, spending, and corporate investment. This blog explains the fundamentals of inflation and interest rates, examines their relationship, explores their impact on consumers and businesses, discusses India's economic experience, compares global trends, and provides key insights for students and investors.
Understanding Inflation
Inflation is the continuous rise in the general price level of commodities and services over a period of time. As prices increase, the purchasing power of money decreases. This means the money that used to buy 12 apples may now only buy 7 apples for the exact same amount. Although the face value of currency remains unchanged, its real purchasing power has declined.
Inflation is measured using price indices. In India, the primary benchmark is the Consumer Price Index (CPI), which tracks changes in retail prices of goods and services purchased by households. Another key indicator is the Wholesale Price Index (WPI), which monitors price changes at the wholesale and producer level.
Moderate inflation is considered healthy for an economy as it indicates expanding business activity, rising incomes, and robust consumer demand. However, excessive inflation erodes purchasing power, makes everyday life expensive, and creates economic instability.
Types of Inflation
Economists classify inflation into distinct categories based on causes and intensity:
- Demand-Pull Inflation: Occurs when aggregate demand for goods and services exceeds aggregate supply. During periods of rapid economic growth, consumers spend more, businesses invest aggressively, and overall demand outpaces production, causing prices to rise.
- Cost-Push Inflation: Driven by increases in the cost of production. Rising wages, expensive raw materials, higher fuel prices, or increased freight costs force manufacturers to charge higher prices to protect operating margins.
- Built-In Inflation: Develops when workers demand higher wages to keep up with rising living costs. Businesses then increase product prices to cover higher wage bills, generating a self-perpetuating wage-price spiral.
- Rate Classifications: Inflation is also categorized by velocity: Mild Inflation refers to slow, manageable price increases (typically under 3-4%); Galloping Inflation occurs when prices surge at rapid double- or triple-digit rates; and Hyperinflation represents an extreme scenario where prices rise uncontrollably, severely damaging currency stability.
What Are Interest Rates?
An interest rate is the cost of borrowing capital or the financial reward for saving money. When a borrower takes a loan from a bank, they pay an agreed interest rate on the principal. Conversely, when depositors place funds in savings accounts or fixed deposits, banks pay them interest.
Interest rates influence almost every aspect of corporate and personal finance: home loans, education loans, working capital loans, vehicle financing, credit card balances, savings yields, and institutional investment returns.
Why Does the RBI Change Interest Rates?
The Reserve Bank of India is mandated to maintain price stability while supporting economic growth. Inflation is one of the primary metrics guiding its Monetary Policy Committee (MPC) decisions.
When inflation increases drastically, the RBI typically raises the repo rate—the rate at which commercial banks borrow short-term funds from the central bank. As borrowing costs rise for commercial banks, they pass these increases on to retail and corporate borrowers. This discourages excessive consumer spending and capital outlays, cooling aggregate demand and curbing price pressures.
During periods of economic slowdown, the RBI reduces interest rates. Lower borrowing costs incentivize business investment, encourage retail spending, and expand credit flow, stimulating economic activity and employment generation.
The Relationship Between Inflation and Interest Rates
| Interest Rate Dynamic | Impact on Inflation | Economic Relationship & Effect |
|---|---|---|
| High Interest Rate | Generally decreases | Expensive borrowing reduces spending and corporate investment, lowering overall demand and easing inflationary pressure. |
| Low Interest Rate | Generally increases | Cheaper borrowing encourages consumer credit and business expansion, which increases aggregate demand and can push inflation higher. |
| Rising Interest Rate | Inflation tends to slow | Central banks tighten policy to control excess liquidity and bring inflation back within target tolerance bands. |
| Falling Interest Rate | Inflation may rise | Lower policy rates stimulate economic activity, increasing money supply and potentially pushing price levels upward. |
| Stable Interest Rate | Inflation remains steady | When demand and supply are balanced, stable rates support steady economic expansion and predictable price levels. |
Impact on Consumers
High inflation increases the prices of essential goods, food, fuel, transportation, healthcare, education, and housing. Families must allocate greater shares of their monthly budget simply to maintain the same standard of living. Individuals on fixed incomes or pensions are especially impacted because their monthly earnings do not adjust automatically with inflation.
However, higher interest rates bring advantages for savers. Fixed deposits and recurring deposit accounts offer higher nominal yields, allowing households to earn better interest income on their saved capital.
Impact on Investors and Financial Markets
Inflation and interest rates are major drivers of asset valuation and portfolio allocation:
- Equities: Higher interest rates generally compress stock market valuations as corporate borrowing costs increase, debt servicing rises, and future cash flows are discounted at higher rates.
- Bonds: Bond prices move inversely to interest rates. When central banks hike rates, yields on existing bonds become less attractive relative to newly issued bonds, resulting in capital losses for bondholders.
- Gold & Commodities: When inflation accelerates sharply, investors often allocate capital toward gold and commodities as tangible stores of value to preserve purchasing power.
India's Experience with Inflation and Interest Rates
India has navigated several distinct inflation cycles over the past decade. Food inflation has regularly been influenced by monsoon patterns, agricultural crop yields, global energy prices, and domestic supply chain logistics. During the COVID-19 pandemic, global supply bottlenecks and elevated commodity prices triggered inflationary pressures worldwide.
The RBI responded proactively by calibrating the repo rate to domestic macroeconomic conditions. During the pandemic downturn, rates were reduced to historic lows to cushion businesses and households. As economic activity recovered and imported inflation rose, the RBI systematically increased policy rates to anchor inflationary expectations and stabilize the Indian Rupee.
Global Perspective
Inflation and interest rate dynamics shape economies worldwide, with central banks taking tailored approaches based on structural conditions:
- United States: The Federal Reserve adjusts the federal funds rate when inflation deviates from its 2% target, impacting global capital flows and dollar liquidity.
- European Union: The European Central Bank (ECB) implements monetary policy across the Eurozone to ensure harmonized price stability.
- Post-Pandemic Inflation Wave: Following global supply disruptions and energy market volatility, many advanced economies recorded their highest inflation rates in four decades, triggering coordinated global interest rate hikes.
- Emerging Markets: Developing nations often face heightened inflation risks due to imported crude oil bills, foreign exchange volatility, and external capital flight when advanced economy interest rates rise.
Conclusion
Inflation and interest rates are two of the most influential economic forces shaping modern society. Inflation dictates the real purchasing power of money, while interest rates determine the cost of capital for saving, borrowing, investing, and consuming. Together, they govern financial markets, household decisions, and corporate balance sheets.
In India, the Reserve Bank of India employs monetary policy tools, especially the repo rate, to balance price stability with sustainable economic growth. For business management students, investors, and professionals, developing a strong understanding of how inflation and interest rates interact is vital for sound financial planning and strategic decision-making in an increasingly interconnected global economy.
Related Articles